Renting vs. Buying a Home: What Lifelong Renters Gain and Lose
Rising home prices are pushing younger Americans to question whether homeownership is still the default path to building wealth.
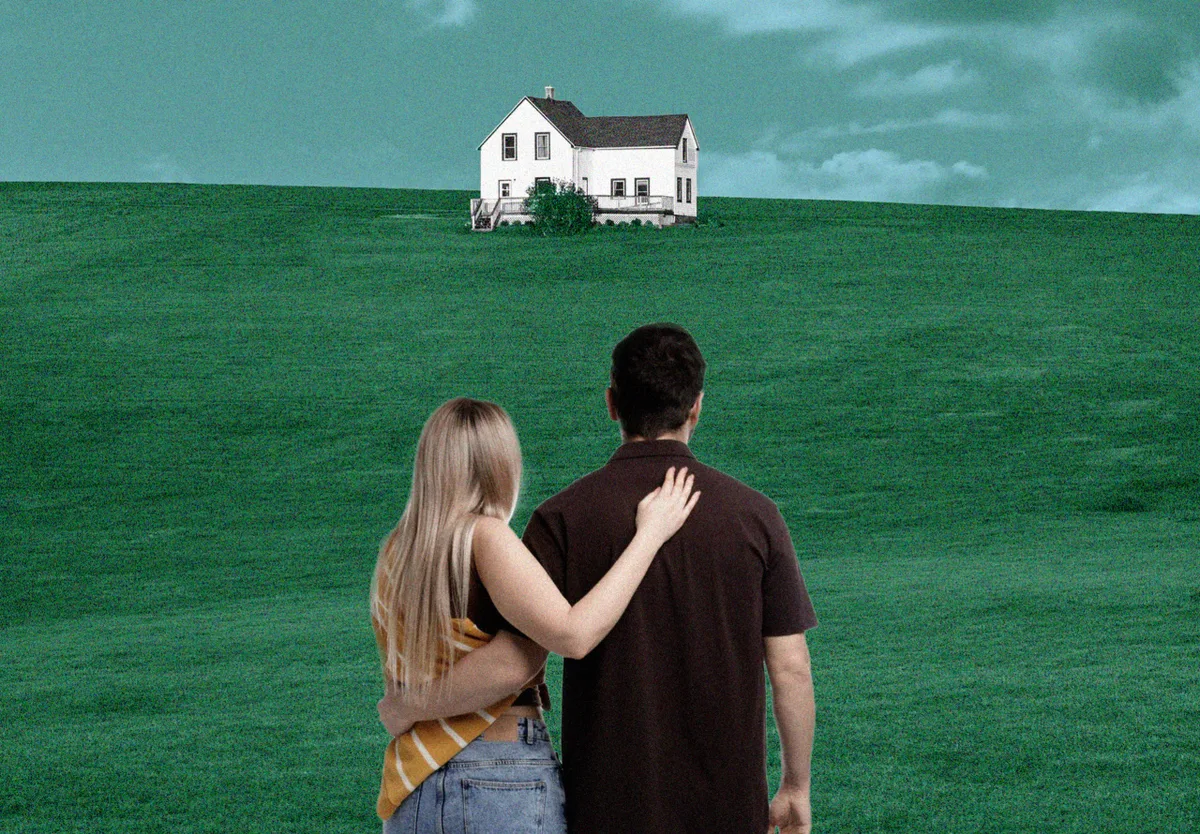
A growing number of Americans in their 20s and 30s are reconsidering one of the most deeply held tenets of personal finance: that buying a home is essential to long-term wealth building. Elevated home prices, high mortgage rates, and constrained housing inventory have made the traditional path to ownership increasingly difficult for younger generations to follow.
The financial calculus around renting versus buying has shifted considerably in recent years. For decades, homeownership was treated as a near-universal financial milestone, with the assumption that building equity over time would outpace the returns available to renters who invested their savings elsewhere. That assumption is now under scrutiny as the upfront costs of buying — down payments, closing costs, and higher monthly mortgage obligations — weigh more heavily against the benefits.
Read more Analyst Predicts Social Security Will Eventually Disappear →
Lifelong renters do surrender certain advantages. Equity accumulation, the ability to lock in a fixed housing cost over time, and the historically appreciating value of real property are all foregone when a household remains in the rental market indefinitely. Homeowners also benefit from tax deductions on mortgage interest and, in many cases, the ability to pass on an appreciating asset to future generations.
At the same time, renting carries underappreciated advantages. Flexibility to relocate for employment opportunities, freedom from maintenance costs and property taxes, and the potential to deploy capital into diversified investments rather than a single illiquid asset are among the benefits renters retain. Financial planners increasingly acknowledge that renting can be a sound long-term strategy depending on local market conditions and individual circumstances.
The debate reflects a broader reassessment of wealth-building norms among younger Americans navigating an economy where traditional milestones are harder to reach on conventional timelines. Continue reading at MarketWatch.com